Business
Why Commercial Cleaning Is Essential for a Healthy and Productive Workplace


A clean office is easy to treat as a background detail, something you notice only when it is missing. But the state of the workplace affects more than appearances. It influences whether staff get sick, how well they focus and the impression the business makes on everyone who walks through the door. Regular commercial cleaning is one of the quieter investments a company can make in its own success.
This is not about chasing a spotless showroom. It is about the practical difference a properly cleaned workplace makes to the people inside it, and which areas matter most.
Keeping germs and viruses from spreading through the office
Offices are high-traffic spaces where people share desks, kitchens, door handles and bathrooms. That makes them efficient at spreading illness, and the cost of that shows up in sick days and disrupted work.
The high-touch surfaces carry the most risk. Door handles, light switches, lift buttons, taps and shared keyboards are touched by dozens of hands a day, and a regular clean that includes disinfecting these spots does more to slow the spread of colds and flu than almost anything else. Workstations deserve attention too, because phones, keyboards and computer mice collect more germs than most people expect. Bathrooms are the obvious priority, both for hygiene and because nobody wants to use a neglected one.
Fewer illnesses mean fewer absences, and that is where the business case comes in. A healthier workplace is a more productive one, simply because more people are at their desks and feeling well.
Allergens and air quality in the office
Dust, pollen and other allergens build up quickly in an office, especially where there is carpet or poor ventilation. For staff with allergies or asthma, that build-up translates into sneezing, itchy eyes, headaches and a general inability to concentrate.
Professional cleaning makes a real difference here because the equipment is built for it. Vacuum cleaners with proper filters remove dust rather than pushing it around, and regular carpet and upholstery cleaning stops allergens from accumulating in the fabric. Ventilation systems also collect dust and bacteria over time, so keeping them clean is part of maintaining good air quality. The result is a space that is more comfortable for everyone, not just the people with allergies.
What a clean space does for focus and morale
The psychological effect of a tidy workplace is easy to underestimate. People notice when their environment is cared for, and it shapes how they feel about their job.
Clutter and grime are distractions. A desk buried under mess or a kitchen that has not been wiped down in days pulls attention away from work and quietly lowers the tone. A clean, organised space helps people concentrate, and it reduces the low-level stress that comes from working in chaos.
There is also the signal it sends. When clients or visitors walk into a clean, tidy office, they read it as professionalism. When staff see the business keeping their workspace clean, they read it as being valued, which supports morale and retention. None of this shows up directly on a balance sheet, but it is part of how a workplace runs.
The areas that need regular attention
Some parts of the office need cleaning far more often than others, and it helps to know where to put the effort.
Bathrooms are the most-used and highest-risk area. Toilets and urinals need frequent disinfecting, sinks and counters collect soap scum and germs, and floors and walls need regular attention to stay presentable.
Kitchens and break rooms are where food spills, crumbs and odours take over. Fridges and microwaves harbour old food and spills, countertops need wiping after every meal, and floors collect dropped food and drink. A clean break room is also one that people actually want to use.
High-traffic areas such as hallways, lobbies and entryways set the first impression. Floors and carpets take the most wear, doors and handles are touched by everyone coming in, and bins need emptying regularly to keep odours and pests away.
Workstations are where staff spend most of their day. Keyboards, mice, phones and screens are touched constantly, so they deserve regular wiping, and a general expectation that desks get tidied keeps the whole office feeling calmer.
Choosing the right cleaning service
The best cleaning arrangement is one tailored to the workplace, and a few things are worth looking for when choosing a provider.
Ask about the products they use. Eco-friendly cleaners that are non-toxic and biodegradable are better for staff and the environment, and more companies are offering them as standard. Check whether they can work around your hours, since many businesses prefer after-hours cleaning so it does not interrupt the day. A provider should also be willing to build a plan around your space rather than selling you a one-size-fits-all schedule.
Reputation matters. Reviews from other businesses, references and any relevant health and safety certifications give a sense of whether a provider will actually deliver consistent, professional work. The cheapest quote is rarely the best value once you factor in reliability.
Questions about workplace cleaning
How often should an office be cleaned? It depends on the size and type of business, but most offices benefit from a clean two to three times a week, with high-traffic areas done more frequently.
Can commercial cleaning be eco-friendly? Yes. Many providers now use biodegradable, non-toxic products, so it is worth asking before you commit.
Which areas need the most attention? Bathrooms, kitchens, high-traffic entry points and shared workstations are the priorities because they are used most and carry the most germs.
How does a clean office affect productivity? It reduces distractions and illness, which supports focus and means more people are at work feeling well.
What should you look for in a cleaning provider? Flexible scheduling, eco-friendly options where possible, a solid reputation and a willingness to tailor the plan to your workplace.
Cleaning as part of how a workplace runs
Commercial cleaning is easy to treat as an expense to minimise, but it behaves more like an investment in the people who make the business work. A clean office keeps staff healthier, helps them concentrate and tells everyone who walks in that the place is run properly. It does not need to be complicated. A sensible schedule, the right products and a provider that understands the space are enough to keep a workplace feeling looked after, and that feeling carries into the work itself.

- The air conditioning is the one system in a car most likely to have been topped up and least likely to have been diagnosed.
- The refrigerant is not a fuel. It circulates, the system is sealed, and if the gas is low then some of it has left through a leak.
- Heat and red dust attack the two parts that have to move air and shed heat, and a dust-packed condenser mimics a gas problem exactly.
- “Never cold”, “cold at speed and warm in traffic” and “cold when you start, warm later” are three different readings, not one fault.
- And the top-up canister half the world’s videos are built around is not the answer here, because handling the refrigerant is licensed work in Australia.
If you are reading this with the engine running and the vents set to cold, and the air arriving at your hand is merely not warm, you are in the exact spot this article is written for. The plan forming in your head, that it just wants a regas, is the most common plan in the subject and often the wrong one. What follows is a reading rather than a repair: what the system is, what this climate does to it, what each symptom points to, and the questions worth asking before anybody touches it. Nothing here teaches you to do the work, deliberately, and the reason why becomes clear in the middle of the piece.
It is a sealed system, and that changes everything
Start with the one piece of understanding the rest hangs on, because it is simple and almost nobody is told it plainly.
Air conditioning is a loop. A compressor moves refrigerant around a circuit: it is compressed, it sheds heat through the condenser at the front of the vehicle, it is allowed to expand, and it absorbs heat from the air inside the cabin at the evaporator. The refrigerant carries heat out of the cabin and hands it to the air passing through the condenser. That is the whole design.
The consequence is this: the refrigerant is not a fuel and it is not a consumable. It does not get used up, burned or spent. It circulates, and it stays inside the system unless it gets out. So when a system is low on refrigerant, something has allowed it to leave, even if nobody can find where yet. And a top-up that makes the air cold again for a season has not fixed anything. It has replaced the evidence.
Now the fairness note, because this cuts both ways: that does not make every warm system a leak. A system can hold the right charge and still blow warm, and the next two sections are about the ways that happens. But it does mean the word “regas” describes a symptom rather than a diagnosis, and the diagnosis is the part worth paying for. None of it makes the routine service the enemy either: the service is where the filter and the visible condition of the system get looked at, and the site’s Why you shouldn’t skip your car’s logbook service argues that case properly.
What the heat and the dust do here
This is the section that makes the fault different in a place like Karratha, and it is about two conditions rather than two parts.
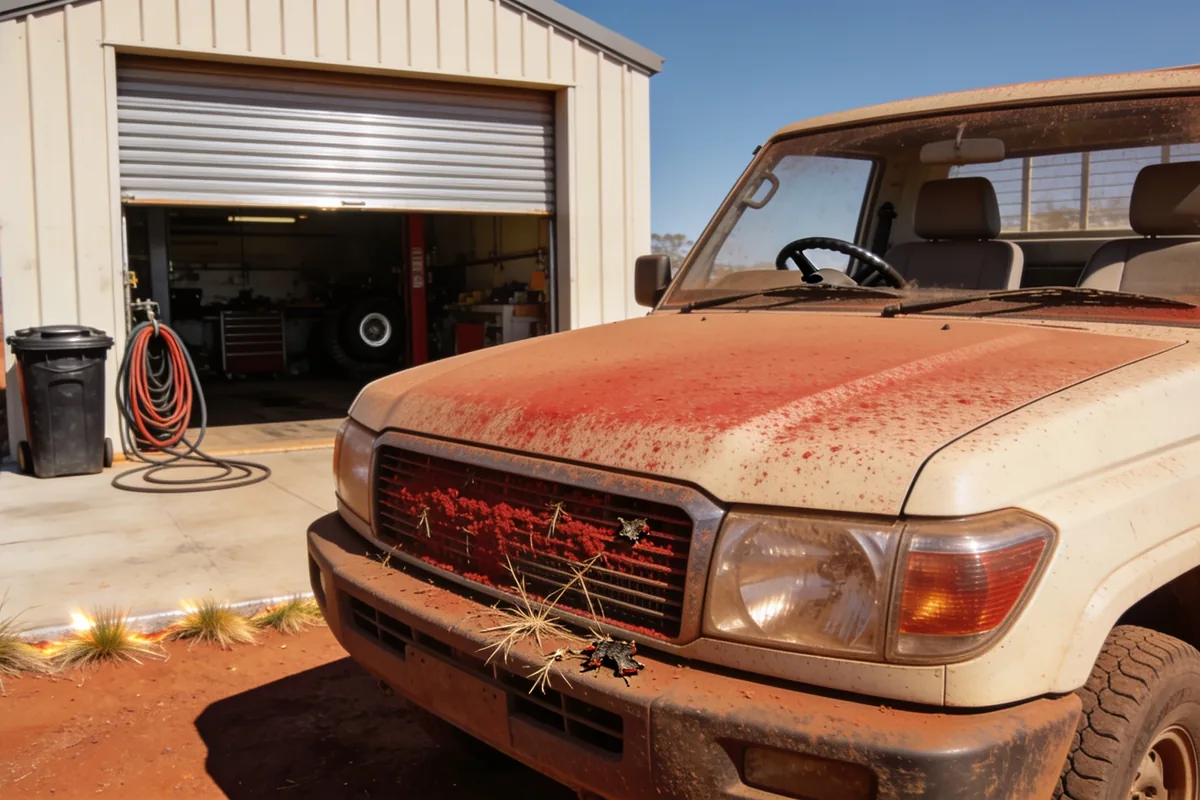
The condenser is a radiator in front of the other radiator. Its whole job is to get rid of heat, and it can only do that when air passes through it. Pack its face with red dust, dried grass and insects, as a Pilbara summer will, and it stops shedding heat exactly when it is being asked to shed the most. From the driver’s seat this feels identical to a gas problem, and it is the one most likely to be blamed on the refrigerant.
The cabin filter is the other end of the same airflow story. A filter loaded with dust reduces the volume of air the driver can feel, and a weak system and a blocked filter are indistinguishable without looking. This is the cheapest part of the whole system to deal with and it is a routine service item, which is worth holding on to when the first quote arrives.
Then the conditions themselves. Sustained heat ages the parts that hold refrigerant in: the hoses, the seals, and the compressor’s own seals. A system that is comfortable in a mild climate can be marginal here, and marginal is the right word, because it fails at the edges. The load matters too. A cabin that has been sitting in the sun holds far more heat than one that has not, so a system with nothing left in reserve fails on the first hot morning of a run and works again in the evening. And a vehicle that sits for a fortnight and is then used hard asks the whole system to perform from a standing start, in the worst heat of the day.
The honest summary: the same fault that is a mild nuisance in a cooler city is the reason a vehicle gets left at home here. That is what makes this a maintenance story rather than a comfort one.
What “not cold” is actually telling you
Read the symptom like a clue, because each one points somewhere different. This section diagnoses nothing and repairs nothing. It narrows the field.
Never cold at all. The system is not moving heat, and the question is whether that is the refrigerant, a compressor that is not engaging, or air that is not reaching the condenser. Three different answers, three different jobs.
Cold at speed, warm in traffic. The classic reading for a system that cannot shed heat when the vehicle is not moving, which points at airflow over the condenser rather than at the charge. Dust, as above, lives here.
Cold when you start, warm ten minutes later. This is the one drivers most often misread as a gas problem, and it usually points somewhere else: something is working at first and then giving up, which is a different investigation.
Cold on one side of the car only. A reading about where the air goes rather than how much refrigerant there is.
And working, but never quite cold enough. The hardest one. “Not cold enough” is a measurement rather than a description, and the honest thing to say is that a workshop has to measure it rather than guess at it.
Every one of those can be a different fault, and the only way to tell them apart is to have the vehicle looked at by somebody with the tools. Which is why the next section is about the licence, and the one after it is about the questions.
The part that is different in Australia
Here is where this article stops being another version of a video, and it is written as a fact about the industry’s licensing scheme rather than as a warning.
Handling the refrigerant in a vehicle’s air conditioning is licensed work in Australia. The licensing body issues its licences by category, and the category that covers the air conditioning fitted to a vehicle is its own; a person licensed to work on a fridge or a building’s system is not automatically covered for a car. A business that recovers, stores or disposes of refrigerant needs its own authorisation to hold the stuff at all, which is why a “regas while you wait” service is a licensed operation rather than a bloke with a can.
And the expectation that matters most to a driver: a licensed technician is expected to find and repair the leak before the refrigerant goes back in. Repeatedly recharging a leaking system is not treated as a method by the industry’s codes of practice. Put plainly, that is what makes the canister-and-gauge approach, the one half the world’s videos are built around, a dead end here. It is not something a household can lawfully do, and setting the rules aside, it would not solve the problem it appears to solve.
What that means for you, positively: a workshop that will not tell you where the leak is has not finished the job, and you are entitled to ask for the diagnosis and for the licence behind the work. Those are ordinary questions, and the answers are the difference between a repair and a repeat.
What to have ready when you ring
A workshop can only diagnose what it is told, and “it is not cold” is the least useful version of the story. Six things make it more useful.
When is it not cold? Always, only when idling, only on the first start of the day, or only after the car has been running a while. Each is a different reading, as the previous section showed.
Has it been topped up before, and when? A system that has been recharged twice is a system with a leak nobody has found yet, and it changes where the investigation starts.
Has anything else changed? A smell, a noise when the compressor engages, a wet carpet in the footwell, a windscreen that fogs more than it used to. Small details, but each one shortens the search.
When was the cabin filter last changed? If nobody can remember, say so: it is the cheapest possible answer and it should be ruled out early.
And how is the vehicle used? Parked in the sun all day, towing, a long idle at a gate, or a fortnight of sitting between swings. This is the kind of context a locally owned Karratha workshop that services petrol, diesel, hybrid and electric vehicles asks about at the counter, and the pattern of use explains a surprising amount of what a system does.
Two things worth knowing before you authorise anything
The money-shaped section, with no money in it, because the principle matters more than any price.
First, a leak that is not found is a charge you will pay for twice. That single sentence is the argument of this entire article. The recharge that skips the diagnosis is not a cheaper repair. It is an instalment on a more expensive one.
Second, the cheap part and the expensive part are not the same part. A diagnosis, a seal, a filter and a compressor are four different jobs with four different sizes, and the question to ask about any quote is which one you are being quoted for. If the answer is a compressor and nobody has shown you a leak, that is worth a second conversation.
And the honest third: an older vehicle’s air conditioning can reach the point where living with it is the sensible outcome, especially if the car does mostly short local trips in the cooler months. A workshop that says so is being straight with you, and the site’s The “I’ll fix it later” car problem that often ends in a massive repair bill is the piece about what happens when a decision like this keeps sliding. The difference is simple: some repairs get worse with time, and air conditioning usually just stays where it is, once you know what you are living with.
One genuinely useful thing before all of that: if the system is cold but the cabin filter has not been changed since the last service, check it first. Nothing else in this article costs less to rule out.
Before you pay for a regas
The short version, in the order it helps.
Does it ever get cold, and if so, when does it stop? Has it been topped up before? When was the cabin filter last changed? Where is the leak, and how was it found? Is the person doing the work licensed for vehicle air conditioning? And what exactly is being quoted, the diagnosis or the repair?
A recharge is the cheapest way to make a leaking system cold for a while. Finding the leak is the only way to stop paying for the same repair. Those are not the same purchase, and the good workshops will not pretend that they are.
Sources consulted: Australian Refrigeration Council information on refrigerant handling licences; your vehicle handbook.

- You can ask the tax office for time, and it has a published process for exactly this.
- A payment plan breaks the debt into smaller amounts, paid weekly, fortnightly or monthly over the shortest period you can manage.
- Two things decide whether it works: whether your lodgements are up to date, and whether the amount you agree to is one you can actually keep paying.
- The interest keeps running while you are on the plan, which is the part that surprises people most.
- And nothing improves by waiting.
You owe the tax office money you cannot pay, you have not dealt with it, and you are not sure whether asking for help makes things worse. Take a breath, because the answer to that last question is no. The tax office publishes a process for people in exactly this position, and using it is what it is there for. Here is what a payment plan is, how it is set up, what the tax office weighs up, and what to do when the answer is not the one you wanted.
Your position, before you ring
0 of 8Four things to write down, and what to do about each. Fill it in before you contact the tax office, and the conversation becomes a conversation rather than a confession.
General information only, not tax advice. This sheet is a place to write down your own position. Nothing on it is a calculation, and no amount, rate, threshold or date appears here. Check your position with a registered tax agent.
If the arrangement changes, say so early. An arrangement that is kept is worth more than one that is not.
What a payment plan actually is
Start with the plain definition, because the plainness is the point. A payment plan is an arrangement to pay a debt you already have, in instalments spread over the shortest possible fixed period. You agree on a sum, and you pay it weekly, fortnightly or monthly until the balance is cleared.
It comes with one condition that people miss, and it matters later in this article: you must also lodge and pay any future tax debts in full and on time while the plan runs. A payment plan is an arrangement about the past, not a change to your ongoing obligations.
Now the paragraph that decides whether the rest of this article is trustworthy, so it goes early.
The debt continues to accrue the general interest charge while you are on the plan, and that charge compounds daily. Read that twice, because it is the single most surprising part of the whole process. A plan is not a pause. It is a way through, and the shortest period you can genuinely manage is the one that costs the least overall. That is also why the right question is never “what is the smallest instalment”, but “what is the largest instalment I can actually keep paying”. The first question feels safer. The second one is the question that finishes the debt.
What a plan is not, in three short lines. It does not reduce the debt. It does not waive the interest. And it is not the right instrument at all if you believe the debt itself is wrong, because that is a dispute, and disputes are a different process. Knowing which of those situations you are in changes what you say on the first call, because a debt that is wrong needs a different conversation from a debt that is right and unpayable. Confusing the two is a common way to lose a month.
How it is set up, and why the route matters
There are three routes, and they are best understood by what they are for rather than by their instructions.
Online, through the tax office’s online services, is the first move for a straightforward individual or sole trader debt, and the fastest path when it is accepted. If your situation is simple and your lodgements are in, this is where to start.
The self-help phone line suits a reader who would rather not do it online, or whose online attempt did not go through. It is the same process with a different front door.
And the enquiry line, with an actual person on it, is for anything larger, longer or more complicated than the standard terms. If you have several debts, or a long-neglected pile of them, start here rather than with the self-service routes. You will spend longer on the call and save yourself a great deal of back and forth.
One more tool to know about: the tax office publishes an online payment plan estimator. It is designed to help you work out what you can afford, and to check whether a schedule meets the requirements before you commit to it. It is a planning tool rather than an application, and running the numbers twice with different amounts costs nothing. It will guide you towards the shortest period you can manage, which is the goal for the reason already covered. There is one real limitation: it cannot be used for super guarantee charge debts, which are handled on their own path.
And the honest word on eligibility. The tax office weighs up many factors, and it may not accept the terms you suggest. It may not accept a plan at all. That is the reality of a process with criteria behind it, and it is not the end of the road. If an online or self-service attempt is knocked back, the tax office’s own published advice is to ring the enquiry line and explain your situation, with your identity information ready. A refusal from a form is not a refusal from a person, and plenty of arrangements are made on the phone. And the order matters here: get the lodgements in first, then talk about terms. The tax office can only work with what it can see, and what it can see is what has been lodged.
What the tax office actually wants to hear
This section is preparation rather than a script. You do not need the perfect words. You need four answers, and then the conversation shapes itself.
What is owed, across which periods. Know the total, and know the parts of it. Income tax accounts and activity statement accounts are handled as separate arrangements, so “I owe the tax office” is not specific enough for either of you. If the total has changed since the letter, say so. If you are not sure what the total is, check that before the call rather than during it.
Whether every lodgement is in. A plan on one debt while another return is outstanding is a conversation that goes badly, and getting your lodgements up to date is often the first practical step before anything else can happen.
What you can pay now, if anything. An upfront payment is a real part of how these arrangements are set up, and offering something genuine is better than offering nothing.
And what you can keep paying. This is the number that decides whether the arrangement survives, which makes it the most important of the four.
Then the paragraph that matters most, written plainly because it is the truth of the situation. The tax office is not assessing whether you are a good person. It is assessing whether the arrangement will hold. That is why a modest plan that is kept is worth more than an ambitious one that defaults, including to you. If a plan defaults, the full overdue balance becomes immediately payable, and the second conversation is harder than the first. None of that is a reason to promise less than you can manage, either. Under-promising is its own kind of default, only slower.
The parts that catch people out
Six failures, ordered by how often they happen rather than how dramatic they sound.
Not lodging because you cannot pay. The obligation to lodge stands separately from the ability to pay. Missing lodgements do not make the debt disappear. They make the conversation worse.
Assuming the interest stops. It does not. The charge keeps compounding daily, which means a plan stretched out for its own sake costs more than one that is not.
Missing an instalment without saying anything. A plan is an arrangement rather than a grace period, and silence is what turns a missed payment into a default conversation. If you are going to miss one, ring before the date rather than after it. There is a difference between an arrangement being amended and one being broken, and timing decides which of those you are in.
Forgetting that future debts must be paid in full and on time. This is the condition from the start of the article, and it is the one most people do not read. A new debt that goes unpaid can undo an arrangement that was working.
Treating several debts as one. Income tax and activity statement accounts need separate plans, and a reader with multiple overdue accounts has to pay each in full or arrange each one. If they do not, firmer action becomes possible, and that is the tax office’s own term for what follows.
And assuming a super guarantee charge debt behaves the same way. It does not. It is handled separately, and it sits outside the estimator altogether.
One more failure, and it is not a mistake so much as a habit. Dealing with the letter and then avoiding the follow-up. If you are on a plan and something changes, in your income, your business or your ability to pay, saying so early is what keeps the arrangement alive. The tax office can work with a change it knows about. It cannot work with one it finds out about later.
When to get someone else to do it
You do not have to make the call yourself. The tax office publishes that a registered tax or BAS agent can request a payment plan on a client’s behalf, which means the conversation can be had by someone who has it every week.
When is it worth doing? More than one debt, or a mix of income tax, activity statement and super guarantee amounts. A pile of lodgements that have not been done, because the order they are dealt with in matters. A debt large enough that the terms are worth arguing about. A business with a cash-flow problem underneath the tax debt, where the tax is a symptom rather than the disease. And any case where you think the debt is wrong, because a dispute is a different process from a plan, and mixing the two helps nobody. It is also worth doing when you have stopped opening the letters altogether, because a fresh set of eyes is what moves that pile, not a fresh wave of willpower.
The honest note on what an agent is for here: not to make the debt disappear, which no one can do, but to get the arrangement right, to have the conversation, and to spot whether a payment plan is the wrong instrument for your situation. That last part is worth the fee on its own. It is also the part a good practice will show you rather than tell you, by asking for the full picture before it asks for anything else. It is the work an accounting and tax practice at Williams Landing that looks after small businesses across Melbourne’s west does with clients in this position, and it is also the argument the site’s Why Waiting Too Long to Contact a Tax Accountant Could Cost You More Than You Think makes from the other direction.
The conversation worth having before the next one
One short section looking forward, because the emergency is this article’s job and prevention belongs to the months after it.
The reason most people arrive at this point is ordinary. A bad quarter. A customer who did not pay. A health event. A business that wound down. Or the simple human habit of putting a letter aside because opening it would ruin a Tuesday. None of that is unusual, and the process exists because a great many people have arrived here before you.
Two habits keep the next problem smaller. Put the tax you have collected somewhere separate as you collect it, rather than treating it as cash that happens to be in the account for now. And look at your position more often than once a year, which is bookkeeping rather than accounting, and it is the part you can fix yourself without anyone’s help. Neither habit is dramatic. Together they turn a crisis into a small administrative annoyance, which is the whole available difference. For the smaller version of these habits, the site’s 9 Money Mistakes That Are Quietly Costing You (and the Simple Fix for Each) covers the ground well.
The first phone call
The sequence, short and ordered, so you can close this tab and do it.
Open the letter and write down the total and the periods it covers. Check whether every lodgement is in, and deal with that first if it is not. Work out what you can genuinely pay now, and each week or month after that, rather than the number you hope will be accepted. Use the estimator, or the sheet above, before you commit to anything. Set the plan up online if that route fits, and phone if it does not. And if a self-service attempt is knocked back, ring and explain rather than stopping.
If it is bigger than one debt or one year, get an agent to ask for you. That is what they are for.
The letter does not get smaller while it sits there, and the interest does not pause. The arrangement, though, is easier to reach than most people expect, and the only thing standing between you and it is a conversation you can prepare for.
General information only, not tax advice. Check your own position with a registered tax agent.
Sources consulted: Australian Taxation Office information on payment plans and on setting up a payment plan.
- Refinancing replaces the loan, not the car. A new contract pays out the old one and you keep driving the same vehicle.
- What changes is the lender, the rate, the term, the repayment and the fees. What does not change is the debt, or the fact that the car is still the security.
- The number that settles more than any advertised rate is your payout figure, and it comes with an expiry date.
- It can be worth doing, and it can be a way of paying more for longer. Both are true, and the difference is usually in the term.
- And there is one case where refinancing is the wrong conversation entirely. That one gets its own section.
Two years into a five-year loan, plenty of people start wondering whether the deal they signed still fits. The offers from other lenders have started arriving, the car is running fine, and the repayments have not moved since the day they were set. Refinancing can be worth doing, it can quietly cost money, and the figure that decides it is not the one in the advertisement.
Is refinancing worth looking at?
Six questions, one plain answer. This does not decide anything for you and it should not: it tells you whether to start asking questions, and what to ask.
Optional
Optional
Answer the questions and your summary will appear here.
The three numbers to get before you ring anyone: your payout figure in writing, the total cost of each option across its whole term, and the comparison rate on the same amount and term.
General information, not financial or credit advice. Nothing here can see your loan, your lender's terms or your circumstances.
What refinancing actually is
Refinancing is a new loan that pays out an old one. You keep the car, the registration stays in your name, and as far as the driveway is concerned nothing has happened at all. What has happened is on the paperwork: the lender, the rate, the term, the repayment schedule and the fees are all replaced by new ones.
That is the whole idea. Refinancing is not trading in, and this article is not about trading in. It is not a top-up either, where you borrow more against the same car. It is the plain version: one debt replaces another, and the amount you owe does not shrink because of it.
Two consequences follow, and they matter.
The first is that a refinance is a new credit contract. The new lender assesses you again rather than taking your old approval as proof of anything. Your income, your expenses and the vehicle all get looked at on their own terms, and the answer can differ from the one you got two years ago, in either direction.
The second is that the debt does not care which lender holds it. The car is still the security, the obligation still exists, and a lower repayment on paper is not the same thing as a smaller debt. Hold on to that one, because it is where the rest of this article lives.
The number to get before anything else: your payout figure
If you take one piece of procedure from this article, take this one. Before you compare anything, ask your current lender for your payout figure in writing.
A payout figure is the amount that clears the loan on a given day. It is not the balance on your last statement, because interest accrues and fees land between statements, and the number moves as the days pass. That is why it is quoted with an expiry date, and why a figure from three weeks ago is a rough guide. Ask how long it is valid for, and ask what it includes.
Two questions come with it, and both change what you do next.
The first is whether there is an early exit or termination fee. Moneysmart’s own guidance is that variable rate car loans usually do not carry one, which is why you should know which type of loan you hold. If yours is fixed, the exit cost is part of the arithmetic. If it is variable, the honest position is usually simpler. Note the word usually, and check your own contract rather than assuming either way.
The second is what the figure does not cover. If there is a balloon at the end of the loan, a residual you agreed to meet in a lump sum, the payout figure tells you what it costs to clear the debt today. It does not make the balloon disappear, and it does not answer whether meeting it or refinancing around it is better for you.
Get the number in writing. Any lender or broker will ask for it, and having it puts you ahead of the person who is still guessing.
When it is actually worth it
There are four honest cases for refinancing, and none of them is about the rate on its own.
The circumstances changed. The loan was sized for a life you no longer have: a different income, a partner, a move, or a business that now needs the car’s capacity for something else. When the shape of the debt no longer matches the shape of the life, replacing it is a reasonable question to ask.
The original deal was never really chosen. Dealer finance taken on the day, at a rate that reflected a borrower with no credit history, is the most common situation in this topic. A reader who now has some history to show may be offered better terms than the ones they signed. The site’s The Most Common Car Finance Mistakes and How to Avoid Them covers how a deal gets built in the first place, and it is the right read if your answer is “I took what was on the desk”.
The structure does not fit any more. A balloon you do not want to meet, or a term still running when the car will not be, are real reasons to restructure rather than to panic.
The car has fallen behind the loan. This is the one to handle gently. If the amount owing is more than the car is worth, refinancing does not fix that by itself. Moneysmart states the position plainly: if you end up having to sell the car to meet the loan debt, the price you get might not cover the debt, and you keep paying off a loan for a car you no longer have. What a refinance can buy here is time, and sometimes that is worth having. It is a conversation to have with someone who can see your whole position before you sign anything.
One qualifier sits over all four: whether any of them applies to you depends on facts this article does not have. This is general information, not advice about your loan.
When it is not worth it, and nobody on page one will say so
Now the half the lender pages skip.
The term reset is the quiet one. A refinance starts a new term, so a borrower three years into a five-year loan who refinances over another five has bought more years of interest, not fewer. The fortnightly repayment can fall while the total climbs. That is the most common way a refinance costs money, and it happens while everything feels like progress.
The costs go into the new loan. Establishment fees, any broker or introducer fee, and the exit cost on the old loan can all be added to the amount financed rather than paid in cash. That makes them invisible in the monthly figure and very real in the total. Ask what is being added, and what the whole thing costs over its life rather than per fortnight.
The rate is not the cost. A lower advertised rate on a longer term is not automatically a saving, because the advertisement does not tell you what happens to the total.
Before you look anywhere else, ask your existing lender what it can do. Staying with the same lender on new terms is a legitimate first move, not a disloyal one, and a lender that wants to keep the business will sometimes find a better structure than its own website is offering.
And the honest line under the whole section: if the loan is nearly finished, or your only goal is a smaller payment without knowing what it does to the total, the answer is usually no. The site’s How to Secure the Best Car Finance Deal: Tips for Negotiating and Saving Money is where the buying side of this sits, and the same discipline applies in both places: know the total before you admire the rate.
The comparison rate, in one plain paragraph
There is one Australian mechanism that makes this comparison fair, and it is called the comparison rate.
Moneysmart puts it plainly: the lender must give you the comparison rate. It is a single figure that includes the interest rate and the fees, and it is useful because the rate in an advertisement is often not the whole cost. When you compare two loans on the comparison rate, you are comparing more of the truth.
One condition matters, and it is the part people skip. Compare the same loan amount and the same term. A comparison rate quoted on a different term or a different amount is not a comparison. It is a smaller number next to a bigger one.
When you meet a rate on a page, treat it as an opening statement rather than a verdict.
Doing it yourself, and what a broker is for
There are two routes, and neither is wrong. Doing it directly means asking two or three lenders yourself. Moneysmart’s checklist is the shape of the questions to ask: the features and what they cost, all of the fees, fixed or variable, the term, and the comparison rate on the same amount and term. It takes an afternoon and a few phone calls, and for a straightforward loan it is a good way through.
A broker is worth having when the file is not straightforward. Self-employed income that needs explaining, a business asset, a credit history with marks on it, or a car older than most lenders like all make the shortlist narrower, and finding that shortlist is the actual product a broker sells. One question sorts a good one quickly: how many lenders can you actually write for? A number that arrives without hesitation is a good sign. A vague answer is an answer.
Two more things about money. The fee structure has to be disclosed, so ask what you are paying and to whom before you sign anything. And you can check that the person arranging credit is licensed, and who they are paid by, rather than taking it on trust.
This is the work a Brisbane finance brokerage that arranges and refinances vehicle finance through a panel of lenders does every day, and the first useful thing a good brokerage does is tell you when the answer is no. If your situation is a business one, the same payout-and-replace logic applies to an asset like a truck, and Planning to Add a Truck to Your Fleet? Here’s What to Know First is where that conversation continues.
If the real problem is the repayment
One situation deserves its own section, and the lending pages never write it.
If you are refinancing because you cannot meet the repayments, a refinance moves the problem rather than solving it. A longer term lowers the payment and raises the total, and the relief is real but temporary in the way that all borrowed time is.
There is also free and independent financial counselling in Australia. It does not sell anything, and it is there for exactly this situation. Asking for help early is the ordinary thing to do rather than the last resort, and the people who do it are not the people who failed. They are the people who got to the phone first.
The three numbers to get before you ring anyone
Close the tab with three things to find, in this order.
The payout figure, in writing and with its date. Everything else is measured against it.
The total cost over the life of each option, not the weekly repayment. If you only look at one figure, make it this one.
And the comparison rate, on the same amount and the same term for every loan you are weighing.
The loan you signed is not a life sentence. It is also not a thing to replace on the strength of one advertisement, and the difference between the two comes down to those three numbers.
General information only, not financial or credit advice. Any decision depends on your own circumstances, your lender’s terms and your own enquiries.
Sources consulted: Moneysmart car loan guidance; ASIC guidance on checking a credit licence.

Car Air Conditioning in a Hot Town: What “Not Cold” Is Actually Telling You

Why Your Mould Keeps Coming Back (and Where the Water Is Coming From)

Where Your Water Is Going: Finding a Leak Before You Call Anyone

The Science Behind Melbourne’s Unpredictable Climate: What’s Really Going On?

Plastic-Free Coffee Makers: Myth or Must-Have?

Zero Waste Toothpaste: What’s Worth the Switch and What to Look For
-
 Melbourne1 year ago
The Science Behind Melbourne’s Unpredictable Climate: What’s Really Going On?
-
Eco Friendly4 years ago
Plastic-Free Coffee Makers: Myth or Must-Have?
-
Eco Friendly4 years ago
Zero Waste Toothpaste: What’s Worth the Switch and What to Look For
-
 Automotive1 year ago
Wet Weather Tyres in Australia: What to Look For and When to Replace Them
-
 Eco Friendly4 years ago
Plastic Free Packaging: How to Keep Your Business Plastic Free
-
 Eco Friendly4 years ago
How Aussie Businesses Can Reduce Plastic Pollution
-
 Home & Garden1 year ago
Boost Productivity and Mood with a Deep Cleaned Space
-
 Food1 year ago
The 9 Best Foods and Drinks to Enjoy Before Bed for Restful Sleep